First-time buyers
Buying Your First Home in Los Angeles County
Your first home should feel exciting, not terrifying. We explain every step before it happens, in plain words, and never rush you into a decision.
When You Don't Even Know What to Ask Yet
One of our first-time buyers told us, "it being our first time, we didn't know much about the process." That sentence sums up how almost everyone starts. You've heard words like escrow and contingency, a friend has an opinion about rates, and every website seems to assume you already know the basics.
You're allowed to not know. Nobody is born understanding how a home purchase works. Our favorite part of this work is watching a buyer go from quietly overwhelmed to confident enough to explain it to their own friends.
This page is the conversation we'd have with you over coffee. No jargon without an explanation, no pressure, and an honest word when waiting a little longer is the smarter move.
Let's talk about your next move
Are You Ready, or Is Next Year Better?
Owning a home builds equity, gives you a place to plant roots, and lets you paint the walls any color you want. It also comes with repairs, property taxes, and less flexibility if you might move for work soon. We'd rather you buy at the right time than buy fast.
A few signs you may be ready:
- Your income has been steady and you expect it to stay that way.
- You have savings for a down payment and closing costs, with some left over for surprises.
- You plan to stay put for several years.
- Your monthly debts, like car payments and credit cards, are under control.
If a couple of those aren't there yet, that's okay. We'll still gladly talk with you, point you to a lender who can map out a plan, and check back in when the timing fits. Plenty of our clients spent a year getting ready, and they were glad they did.
You Probably Need Less Than You Think
The single most common reason people in this valley put off buying is a down payment number they invented. Twenty percent is not a requirement. It never was.
There are loans at 3 to 3.5 percent down. If you have served, VA is zero down, and with full entitlement there is no VA loan limit on a zero-down purchase, which opens neighborhoods most first-time buyers rule out.
The California Housing Finance Agency runs down payment assistance that pairs with a first mortgage for qualified first-time buyers. There are income limits, a purchase price cap, and a homebuyer education requirement, and not every lender is approved to originate them, so ask specifically rather than assuming.
On top of the down payment, plan for closing costs of roughly 2 to 3 percent of the price, an inspection plus its specialist follow-ups, and a reserve for moving and the first few months.
Talk to a lender before you start saving toward a target. In more cases than you would expect, the answer is that you could buy sooner than you planned.
You Probably Need Less Than You Think
Less than you have been told
What Actually Decides What You Qualify For
Not your savings. Your credit and your debt-to-income ratio.
Which means the most useful thing you can do before buying is usually not saving another $5,000. It is paying down a card, or not opening a new one, or leaving that car loan alone until after closing.
Get a real pre-approval, not a pre-qualification. Pre-qualified means somebody took your word for it. Pre-approved means a lender looked at your documents, and a seller can tell the difference immediately.
Two things to avoid once you are approved: do not open new credit, and do not change jobs if you can help it. Lenders re-verify before closing and both have killed deals days out.
Build the Real Monthly Number
The mortgage payment is not the payment. In this valley, the difference can be several hundred dollars a month.
The full number is principal and interest, property taxes, homeowners insurance, HOA dues if the tract has them, and Mello-Roos if a community facilities district applies.
Mello-Roos is worth understanding before you fall for a house. It funds infrastructure, schools, roads, sewers, and parks. By law it is never calculated on your assessed value. It runs off a formula tied to square footage, lot size, or land use, so two neighbors can pay very different amounts. In established Santa Clarita tracts the charge commonly lands somewhere around $1,000 to $3,500 a year on top of your base taxes, and the newest communities run higher. Bond-funded districts typically run 20 to 40 years from formation, and the seller must give you a notice naming the district, the current tax, the maximum authorized, the escalation cap and the expiration date.
A cheaper home with dues and Mello-Roos can cost more every month than a pricier one with neither. Your lender qualifies you on the monthly number, so that is the number we work from.
A Quick Translation of the Words You'll Hear
Here is something nobody says out loud. In your first real meeting with a lender or an agent, somebody is going to use six or seven of these words inside a single sentence, and most people nod along rather than stop a professional mid-thought to ask what one of them means. Then a week later a form shows up using the same words, and the nodding catches up with you.
So read these once now, while nothing is at stake and there is no deadline attached. You do not have to memorize them. You just need enough of a handle that when one comes up you can say "hold on, explain that part to me again," which is honestly the most valuable sentence a first-time buyer owns.
- Pre-approval: a lender's written confirmation of how much they're willing to lend you after reviewing your documents.
- Offer: your written proposal to buy, including price, deposit, timeline, and conditions.
- Contingency: a condition in your contract, such as a satisfactory inspection or appraisal, that protects your ability to back out or renegotiate within a set window.
- Earnest money deposit: money you put down after your offer is accepted to show you're serious. It's held by escrow and applied toward your purchase.
- Escrow: a neutral company that holds the money and paperwork until every condition is met.
- Appraisal: the lender's independent opinion of what the home is worth.
- Title insurance: protection against problems with ownership history, like an old lien nobody disclosed.
- HOA and Mello-Roos: monthly association dues and a special property tax that some communities carry. Both affect your payment.
And if a word comes up that is not on this list, ask us. There is no version of this where you were supposed to already know.
How You Go From Renter to Homeowner
First, the groundwork. We meet, talk about what home means to you, and connect you with lenders so you can get pre-approved. Before touring, we review and sign a written buyer agreement together that explains our role and how we're paid, and we answer every question about it.
Then, the search. We set up homes that match your budget and must-haves. Send us your wish list any time through our custom home search request. When we tour, we show you what to look at beyond the paint: the age of the roof, signs of water damage, how the lot drains.
Next, the offer. We pull recent sales so you know what the home is likely worth, then write an offer that fits your comfort level.
After that, escrow. Inspections, the appraisal, final loan approval. We keep a calendar of every deadline and tell you what's coming before it arrives.
Finally, the keys. A last walkthrough, your signatures, and a moment we never get tired of. Our buying process page covers each stage in more depth.
Where a First Home Is Realistic Here
It depends on which one matters more to you, and being honest about that up front saves months.
Lowest entry price generally means condos and townhomes, and the older pockets of Newhall and Canyon Country. Watch the HOA dues, because they change the monthly math.
A yard and space usually means looking further out or older, and budgeting for updates.
A specific school narrows the map first and everything else works around it. Assignments depend on the exact address and boundaries change, so we confirm with the district before you write.
A VA benefit changes the math completely and is worth planning around.
Tell us which of those you are and your actual pre-approval number, and we will tell you straight whether an area works or whether another one gets you more. We would rather say so early than walk you through houses that were never going to fit.
How to Actually Win a House
First-time buyers lose homes to the same few things, and all of them are fixable in advance.
Be genuinely ready. Fully approved, documents in hand, decided about what you will and will not do. The strongest offer is usually the one written fastest by the person who already thought it through.
Work out what the seller actually wants most. It is not always the highest number. Certainty, a clean timeline, a rent-back so they are not moving twice. Those can beat more money.
Know your walk-away number before you are emotional. We will hold you to it, and that is the job.
And a practical one: a home in an HOA has rules that outlast your enthusiasm. Read the CC&Rs before you remove contingencies, not after.
How to Actually Win a House
First night
Patient Answers, as Many Times as You Need Them
Since 2004 Michelle has helped people buy their first homes, and many of them come back to us when it's time for the next one. Most of our business now comes from past clients and their referrals.
A first-time buyer wrote, "They never pressured us to rush a decision." That's the standard we hold ourselves to. Ask the same question three times. Text us at night. Tell us when a house feels wrong even if you can't explain why. We'll listen, and we'll tell you honestly what we see.
You Are Not Behind
A lot of first-time buyers arrive apologetic, like they should have done this five years ago. You do not owe anybody an explanation for your timeline.
What we can do is give you real numbers so you are deciding with facts instead of a feeling. Sometimes the honest answer is that waiting six months and clearing a debt puts you in a better house. We will say that too.
If you would rather just ask somebody, call or text Michelle at 661-219-5517. She answers her own phone, there is nothing to sign, and no first-time buyer question is too basic to ask out loud.
Send us what you are looking for through our custom home search, or read how the buying process works start to finish.
Frequently Asked Questions
Do I need 20 percent down to buy my first home?
What credit score do I need?
Are there first-time buyer programs in California?
How much should I save beyond the down payment?
What does it cost to work with you as a buyer?
How long does it take to buy a first home?
Should I buy a condo or a house for my first home?
What if I find a home before I'm pre-approved?
Do I need a home inspection if the house looks fine?
Can my parents help with my down payment?
Keep exploring
Ready to make your move with Dubner Real Estate Group?
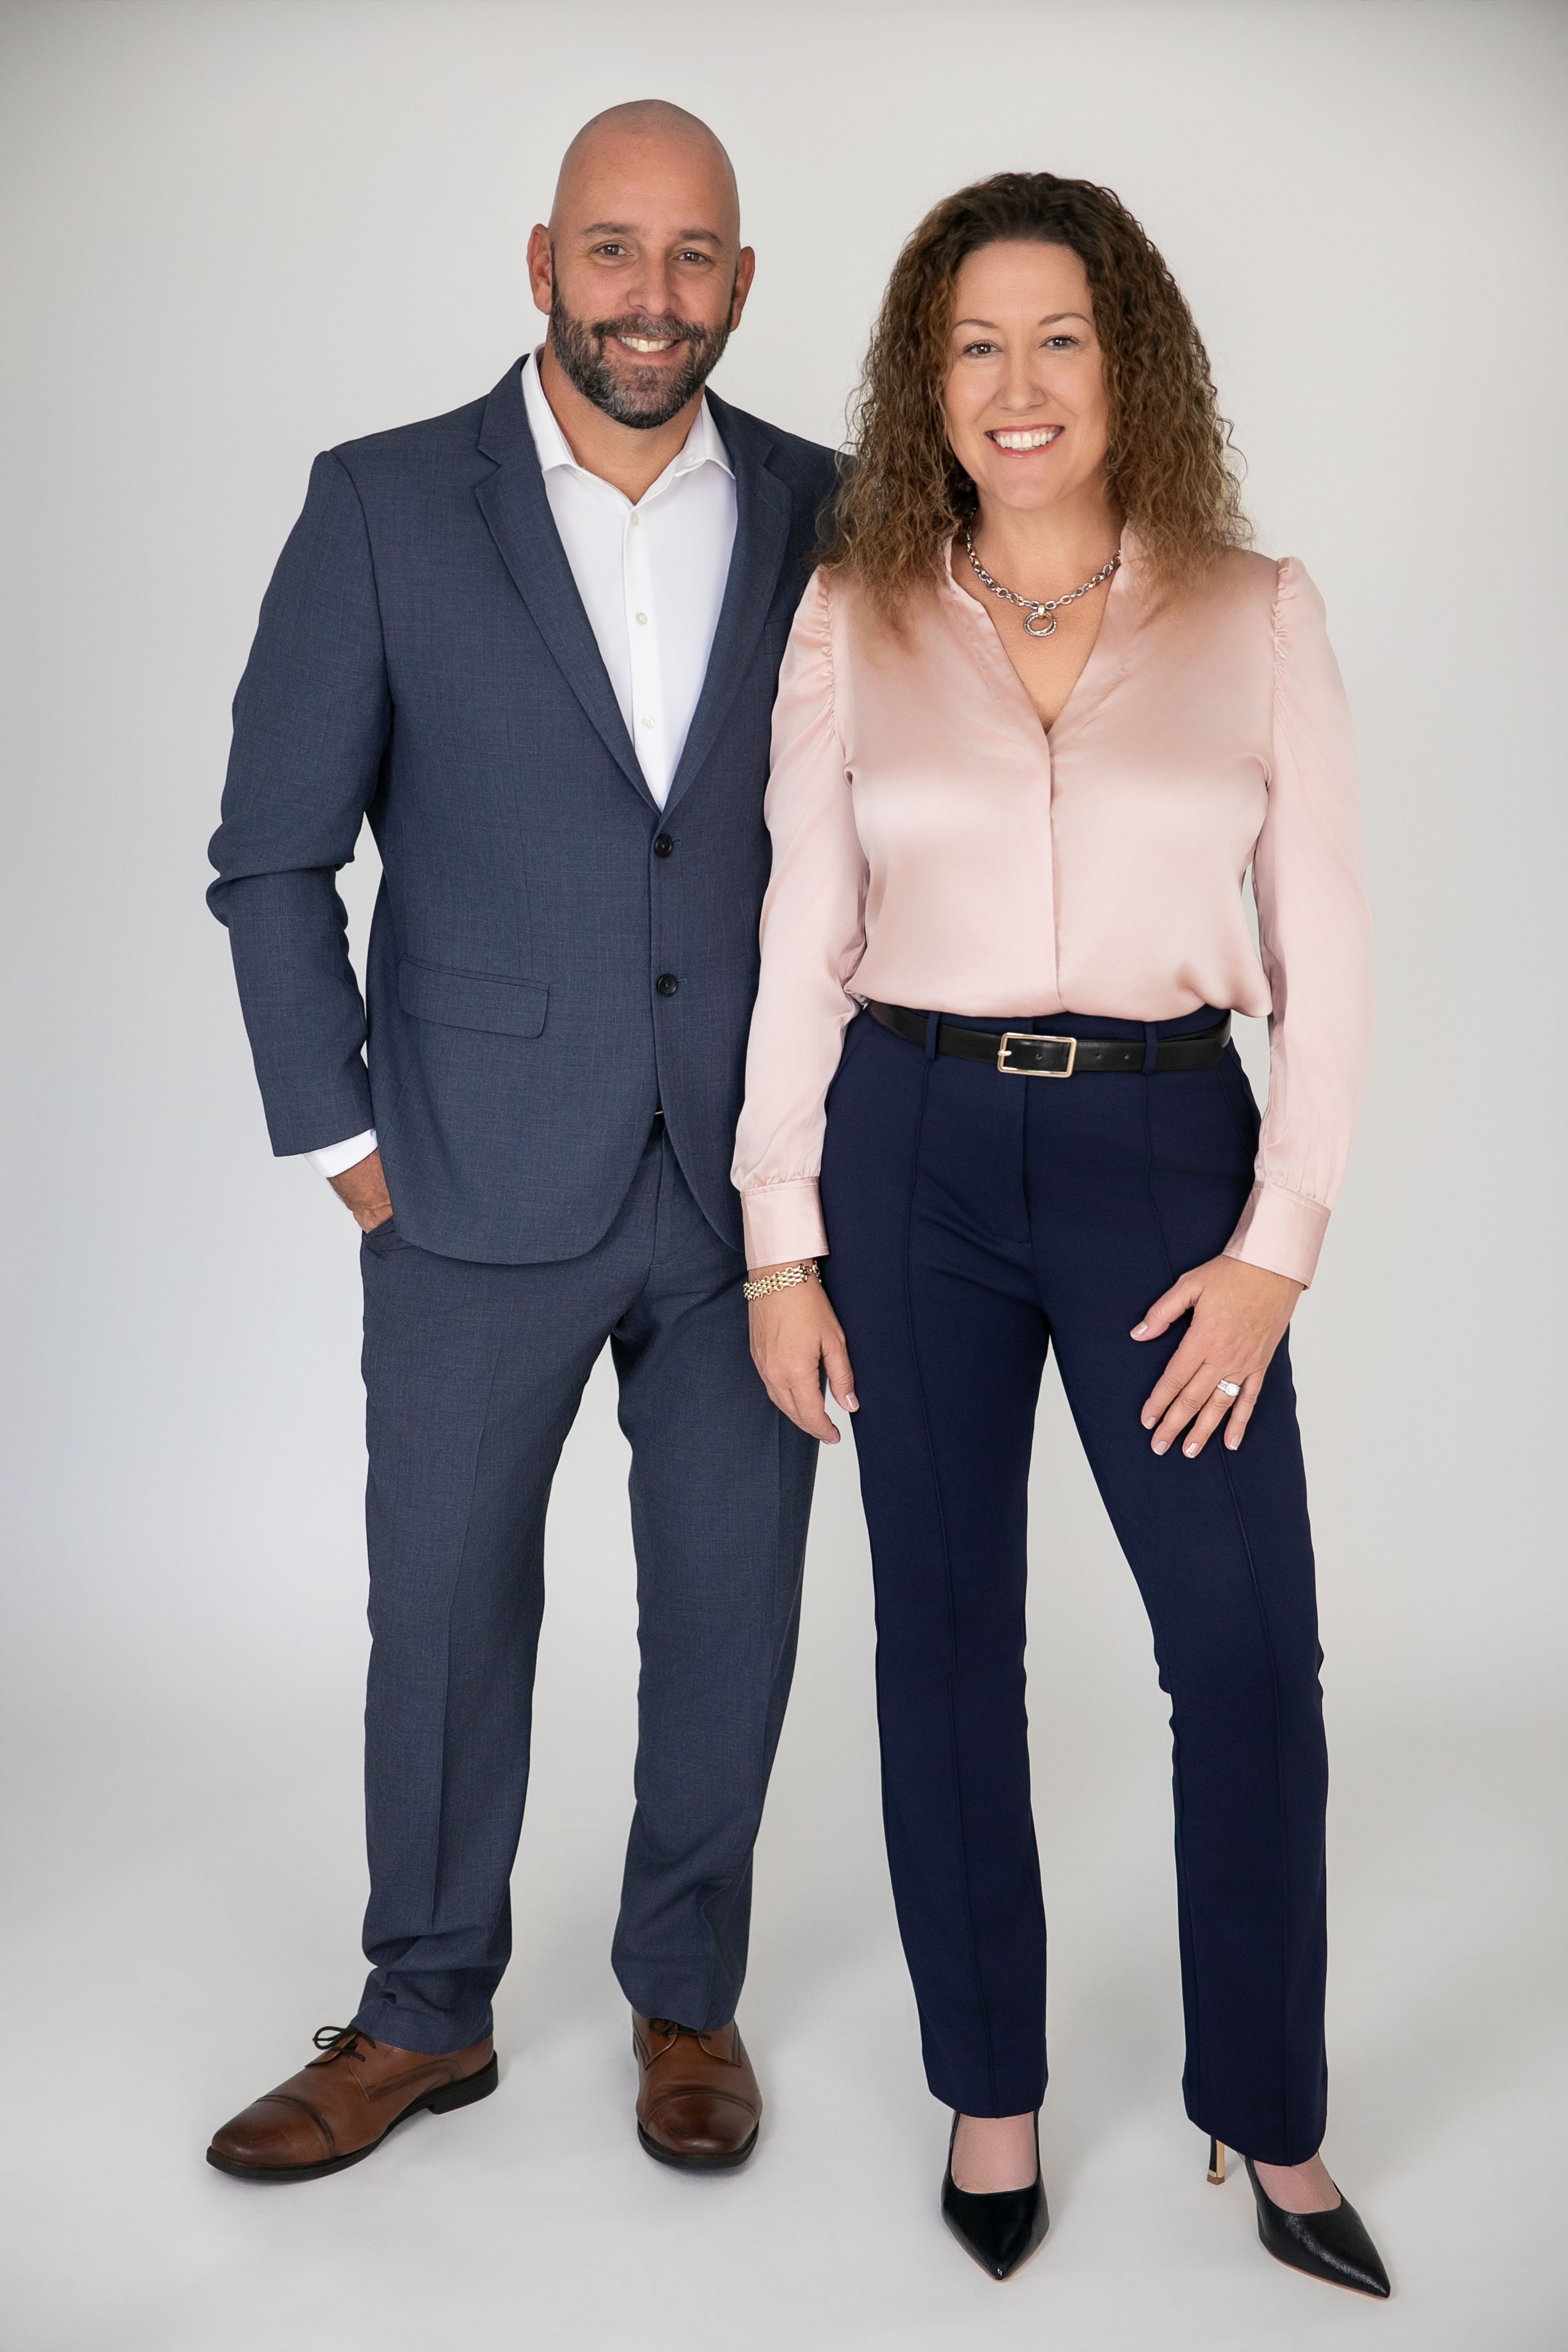
Meet the team
You would be working with our team
We are Michelle and Jon Dubner, husband and wife, and Dubner Real Estate Group is ours. Our team is here to serve you: to understand what you are hoping for, walk you through it step by step, and make sure you get there. Michelle answers her own phone and is quickest by text, so ask us anything, at any point, however small it feels.
Michelle Dubner DRE #01496647 Jon Dubner DRE #02118617 Equity Union