The buying process
How We Help You Buy
Pre-approval, the search, writing an offer that holds up, inspections, escrow, and closing day. Every step, in order, with the California deadlines that actually apply.
The short version
Most agents start by showing you houses. We start by getting you ready to actually win one.
The buyers who lose the home they wanted are almost never the ones who searched too slowly. They are the ones who were not ready to write a strong offer on the Tuesday it mattered. So our process runs on four steps: Ready, Educated, Aligned, and Locked.
Below is the whole thing, including the parts nobody explains until you are already in the middle of them: what the money actually looks like, what happens in escrow week by week, and what your contingencies really protect.
Tell us what you are looking for
Ready: Pre-approved and represented before you tour
Before we walk into a home together, two things happen.
You get pre-approved, properly. There is a real difference between pre-qualified and pre-approved, and sellers know it. Pre-qualified means a lender listened to you describe your finances. Pre-approved means they pulled credit, reviewed income and assets, and issued a letter they will stand behind. The strongest version goes further: fully underwritten up front, so the only thing left is the property itself. In a competitive situation that letter is worth real money.
We will introduce you to lenders we actually trust, meaning they answer the phone on a Saturday and they do not surprise anyone three days before closing. Talk to more than one. Rate matters, but so does whether they will perform.
Here is what that letter actually buys you, because nobody explains this part. A seller is not just reading your price. They are reading how likely you are to close, and the thing that tells them is your contingency calendar. The California purchase agreement defaults to seventeen days on loan, appraisal, and inspections. When your financing is already underwritten, we can write those periods shorter, and a seller reads a short timeline as a deal that is actually going to happen.
That is how you win when you cannot be the highest offer. Put two buyers at the same price in front of a seller and the one who can get to a firm deal faster takes the house. We have used exactly that to beat higher offers, and it costs you nothing but being prepared.
It protects you too, which is the part people get backwards. Your deposit goes at risk the moment your contingencies come off. If you are ahead of your lender, you remove them on the date you promised because the work is genuinely finished, not because the calendar ran out and you are hoping. A short timeline you can actually hit and a short timeline you are gambling on look identical on paper and are completely different things.
And it gives you something to trade. Plenty of sellers care more about the closing date than the last five thousand dollars, because they have a place they need to be. If your loan is ahead of the paperwork, you can offer to close early and mean it. That is a real negotiating chip, and you only have it if you did this step first.
We put our agreement in writing. Since January 1, 2025, California has required a written agreement between a buyer and their agent before touring homes. That came from AB 2992, and it followed the nationwide practice change in August 2024, which is why you will see both dates cited. That is a good change. It means the conversation about what we are owed happens at the beginning, in daylight, instead of somewhere in the middle. You will know the number before you see a single house.
How We Help You Buy
What buying actually costs, up front and at closing
Almost everyone underestimates this, and it is better to know now.
Earnest money deposit. Commonly one to three percent of the purchase price, wired to escrow within about three business days of acceptance. It is not an extra cost; it is credited to you at closing. But it is genuinely at risk once you remove your contingencies, which is exactly why the contingency dates matter.
Down payment. Whatever your loan requires. Conventional loans go as low as three percent for qualified first-time buyers. FHA is 3.5 percent. VA can be zero down. Twenty percent avoids mortgage insurance but is not a requirement, and waiting years to reach it while prices move is not automatically the better plan.
Closing costs. Generally two to five percent of the purchase price for a buyer in California: lender fees, appraisal, title insurance for the lender, escrow fees, recording, and prepaid property taxes and insurance. On many transactions the seller contributes toward these as a concession, which is negotiated per deal.
Inspections. A few hundred dollars for a general home inspection, more if you add a sewer camera, roof, pool, or foundation specialist. You pay these during escrow, out of pocket, and you pay them whether or not the deal closes. That feels bad when a deal dies, and it is still the best money you will spend.
Ongoing, after closing. Property taxes in Los Angeles County run roughly 1.1 to 1.3 percent of purchase price annually, and many newer Santa Clarita Valley neighborhoods add a Mello-Roos special assessment on top. Then homeowners insurance, which in parts of this valley is affected by fire hazard zone designations, plus any HOA dues. We put all of it in front of you on a specific house before you write an offer, because the payment that matters is the real one.
Educated: An honest look at what your budget buys
We show you what your number actually gets in the neighborhoods you like, before you fall for something out of reach. This step saves people months.
Sometimes the honest answer is that the house you described does not exist at that price in that neighborhood, and then you have a real choice to make: a different neighborhood, a different house, or more time to save. All three are fine. Finding out in month six is not.
This is also where we talk about what each community in this valley is actually like day to day, which is not what the listing photos show. Valencia, Saugus, Canyon Country, Newhall, Stevenson Ranch, and Castaic are genuinely different from each other on commute, schools, lot size, HOA, and Mello-Roos, and the difference shows up in your monthly payment as much as the price does.
Aligned: A search built on what actually matters to you
Instead of touring everything on the market, we build the search around your real life: your commute on a Tuesday at 7:40am, not in theory; which school boundary the house is actually in, which is not always the school that is closest; whether you need a yard the dog can be let out into without supervision; whether a two-story is going to be a problem in fifteen years.
Then, in each home, we tell you what we see. The good and the not so good. A sloped driveway you will hate in the rain, a bedroom that only works as an office, a neighbor's second story looking straight into the primary bedroom. You will tour fewer houses, and the ones you see will be worth your Saturday.
Tell us what you are picturing and we will set the search up and call you to go through the results together.
Aligned: A search built on what actually matters to you
What it costs to live there
Writing an offer that actually gets accepted
Price is one term out of many, and in a competitive situation it is often not the one that wins.
The strength of your financing. A fully underwritten pre-approval from a lender the listing agent has heard of beats a higher offer from a name nobody recognizes. We will have our lender call theirs before we write, which sounds small and is not.
Your deposit. A larger earnest money deposit tells a seller you are serious, because it is your money at risk.
Your contingency periods, which is where most offers are actually won. The standard form defaults to 17 days for all four of your contingencies. Shortening them makes an offer read as far more solid to a seller, and it is often worth more than a few thousand dollars on the price. This matters most in exactly the situation where you cannot simply outbid everyone.
But you can only shorten what you can actually perform. A ten-day loan contingency from a buyer whose lender has not started underwriting is not a strong offer, it is a broken one waiting to happen, and experienced listing agents can tell the difference. That is the real reason we push so hard on being ready before you tour: a fully underwritten pre-approval is what lets us shorten the timeline honestly. Preparation is leverage, and it is the one form of leverage that does not cost you money.
We shorten where the risk is genuinely manageable and we do not where it is not. And we will never quietly waive your inspection contingency to win a house. If waiving something is the only way to compete for a particular home, we will tell you exactly what you are giving up and let you decide with your eyes open.
The dates. Sometimes the seller needs three extra weeks, or a rent-back after closing. Giving them the date they need can be worth more to them than several thousand dollars, and it costs you nothing if your own timeline allows it. We ask the listing agent what the seller actually wants. Most people never ask.
An appraisal gap, when it is warranted. In a multiple-offer situation, agreeing to cover some amount of a low appraisal out of pocket makes an offer much stronger. It also means real cash, so we only raise it when it fits what you have and you understand it.
Locked: Escrow, week by week
Your offer is accepted. Escrow on a financed purchase in California commonly runs 30 to 45 days. Here is what is happening inside it.
Days 1 to 3. Escrow opens and you wire your deposit. Call escrow at a number you looked up yourself to confirm wire instructions before sending anything. Wire fraud in real estate is real, it is common, and the money does not come back.
Days 1 to 7. The seller's disclosures arrive: the Transfer Disclosure Statement, the Seller Property Questionnaire, the Natural Hazard Disclosure report, HOA documents if there is an HOA, and Mello-Roos information. Read all of it. We read it with you and tell you which parts actually matter.
Days 1 to 17. Your inspections. A general home inspection at minimum. We usually recommend a sewer camera on any older home, and specialists for the roof, foundation, or pool when the general inspector flags something. On the standard C.A.R. purchase agreement the default is 17 days for all four of your contingencies: investigation, appraisal, loan, and homeowner's insurance. Those are negotiated on the contract, so check the dates on what you actually signed. We track them for you either way.
Around day 10 to 17. The request for repairs, if there is one. This is a second negotiation. You can ask for repairs, a credit, or a price reduction, and the seller can say no. What you should not do is nickel-and-dime a seller over items you knew about when you wrote the offer.
By day 17. The appraisal. The appraisal contingency runs the same 17 days as the others. If it comes in low, we solve the gap: you bring cash, the seller comes down, you split it, or you walk with your deposit intact if your appraisal contingency is still in place.
Day 17. Contingency removal, and all of your contingencies are due that day. Nothing in California removes automatically. You sign a written Contingency Removal form. Until you sign, your protection is alive no matter what the calendar says, and after you sign, your deposit is genuinely at risk. We will not let you sign that form until you have everything you need to decide.
The last week. Loan documents, your final walk-through, signing with a notary, funding, and recording, in that order. In California the home is yours when the deed records with the county, and recording happens the morning after your loan funds, not the morning after you sign. In practice you sign a couple of days ahead, the loan funds the next day, and the deed records the day after that. If you sign very early in the morning it can occasionally fund the same day, but we plan on the normal sequence rather than the exception.
Locked: Escrow, week by week
Every date tracked, so none of them pass you
Closing day, and the week after
The walk-through is not a formality. It is your last chance to confirm the home is in the condition you agreed to, that agreed repairs were done, and that everything included in the sale is still there. Run the water. Flip the breakers. Open the garage door. Check the appliances that are staying.
After recording, you get keys. Then a short list of things people forget: change the locks, set up utilities in your name before you move rather than after, find the main water shutoff and the electrical panel on day one, and put the closing statement somewhere you will find it next April, because parts of it matter at tax time.
And we are still here after closing. Most of our business comes from people we helped years ago, so if you need a plumber, a contractor, or a straight answer about whether an upgrade is worth doing, call us.
Where to start
You do not need to be pre-approved to call us. Plenty of people start the conversation a year out.
Tell us what you are looking for and we will build the search, or call or text 661-219-5517.
If your situation has something particular in it, we have a page for that too. Read about buying your first home, buying with a VA loan, moving here from out of the area, selling and buying at the same time, or buying an investment property.
Frequently Asked Questions
Does it cost anything to work with you as a buyer's agent?
How much money do I actually need to buy a house in California?
How long does it typically take to buy a home in Santa Clarita?
What's the difference between pre-qualified and pre-approved?
Should I waive my inspection contingency to win a house?
What happens if the appraisal comes in below my offer?
What is Mello-Roos, and does it apply to me?
Can I back out after my offer is accepted?
What if I need to sell my current home at the same time?
Do I need a home inspection if the house is brand new?
Keep exploring
Ready to make your move with Dubner Real Estate Group?
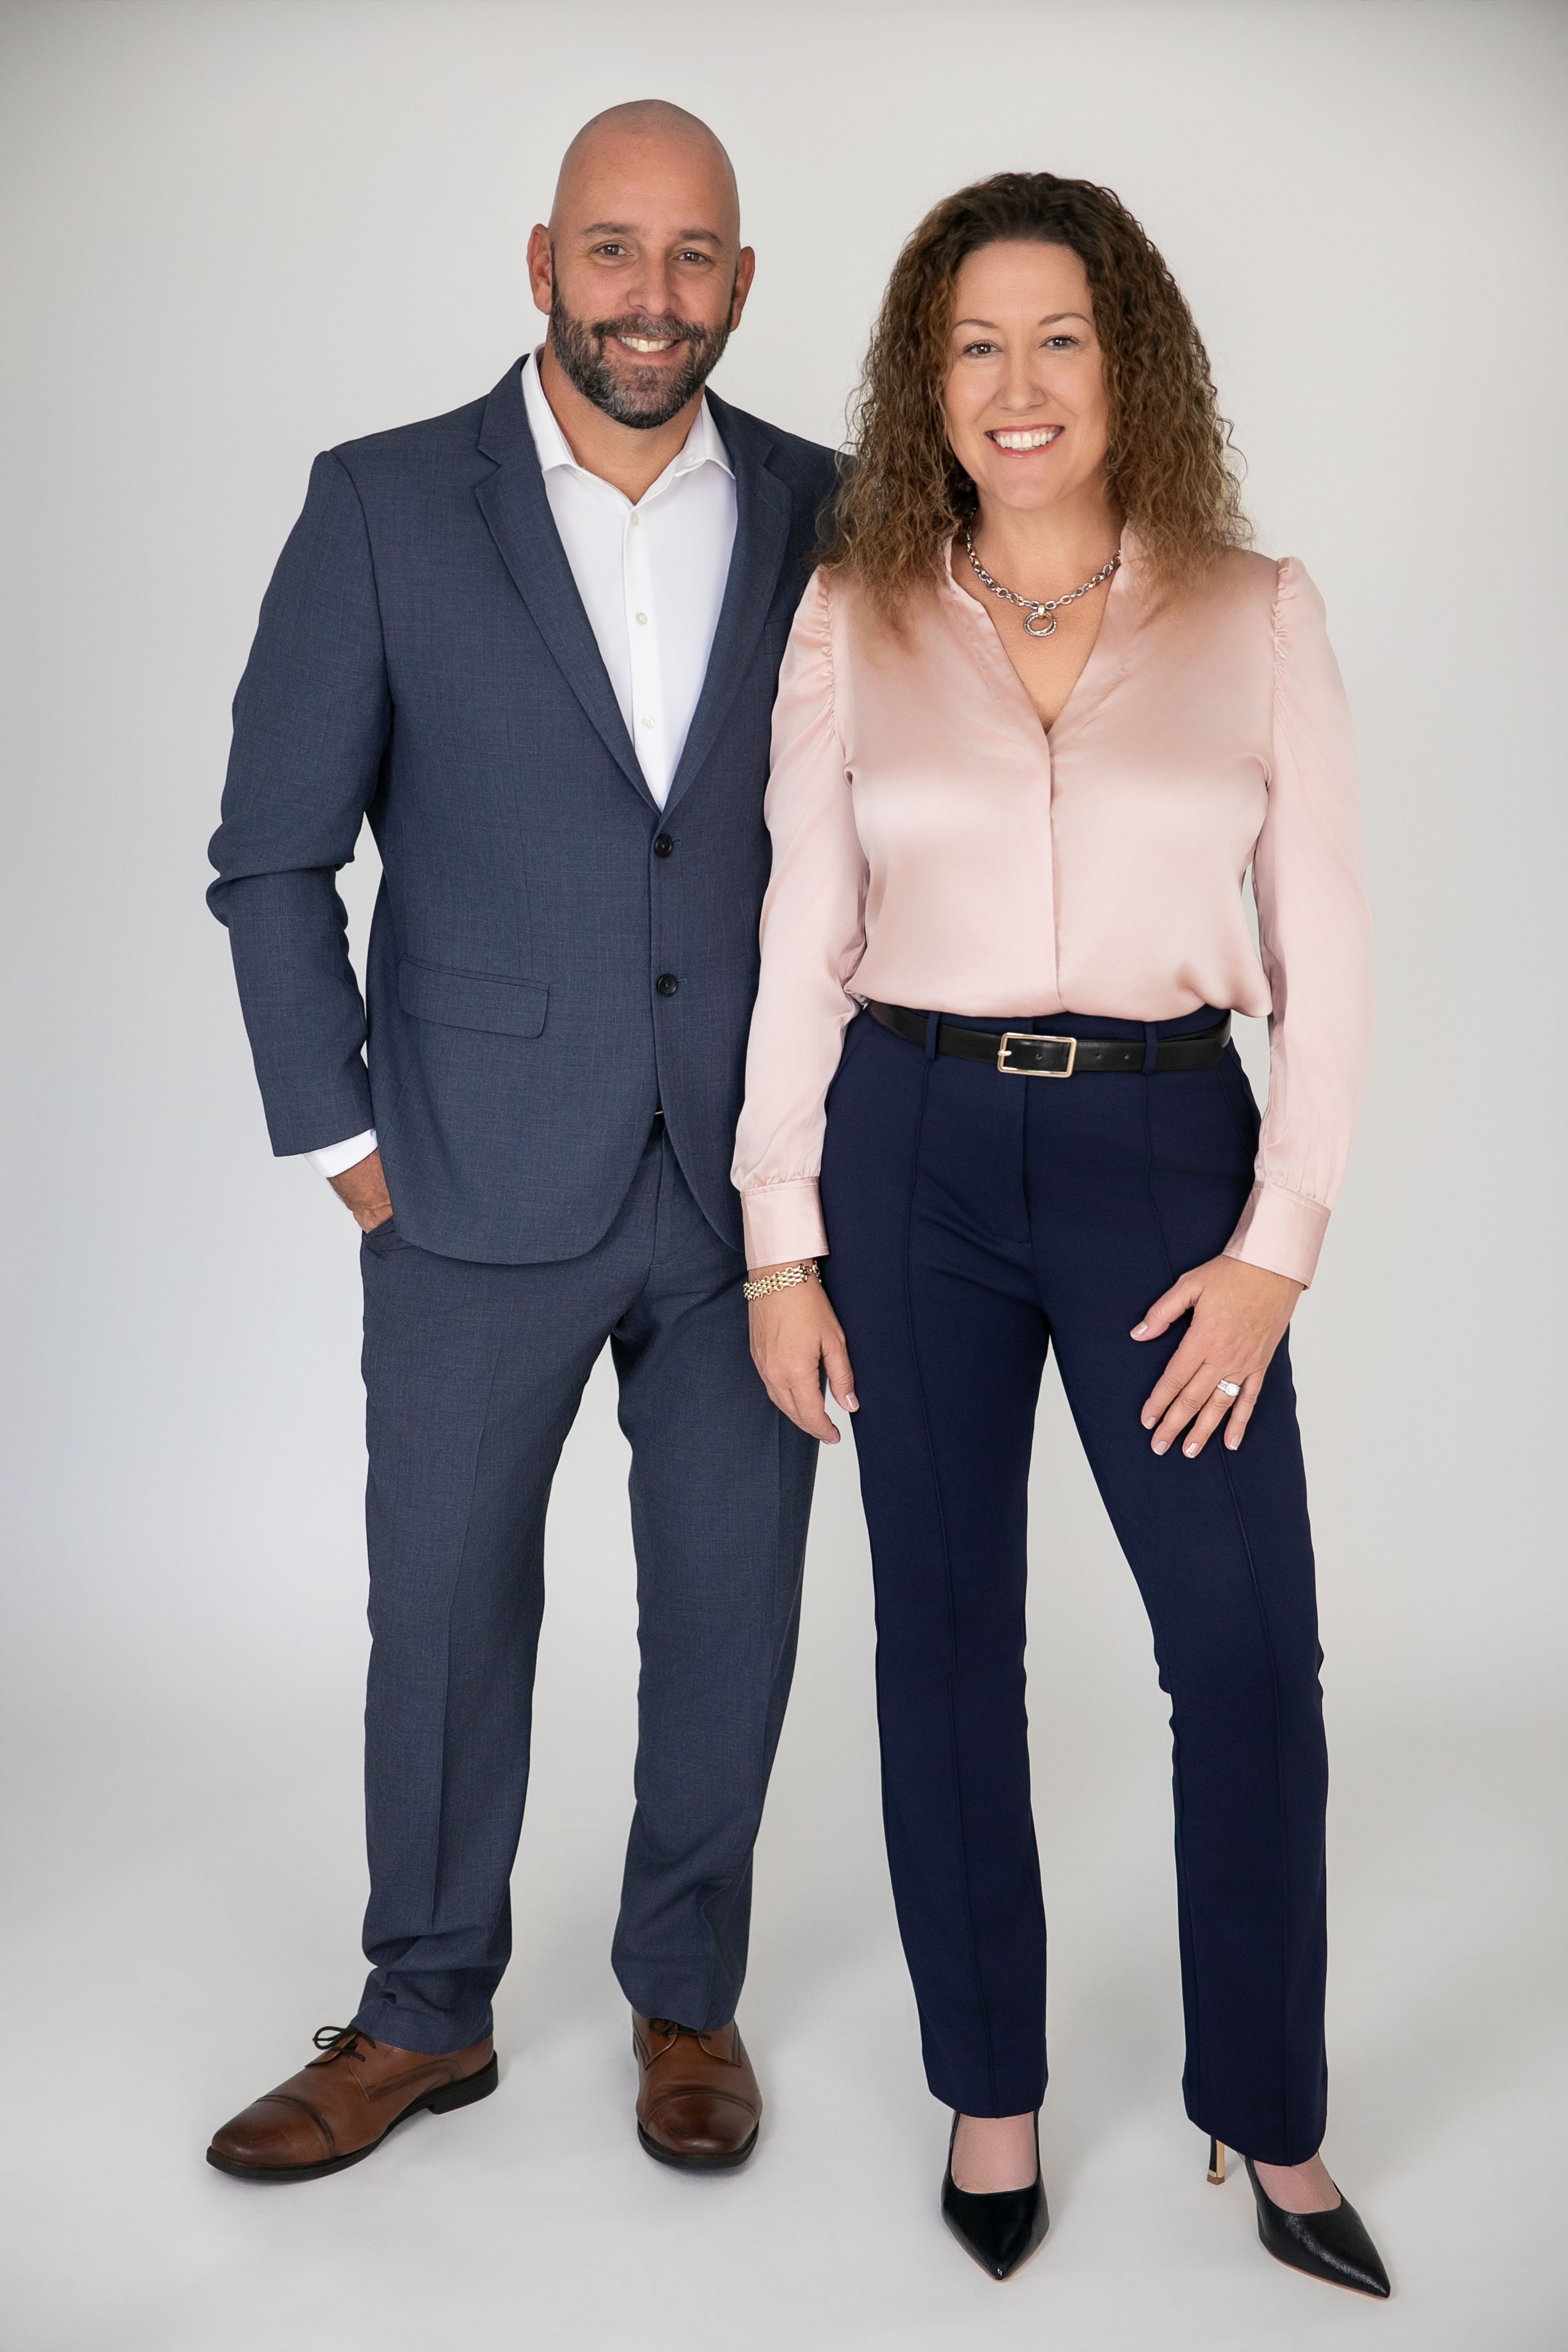
Meet the team
Our team beside you at every step
We are Michelle and Jon Dubner, husband and wife, and Dubner Real Estate Group is ours. Our team is here to serve you: to understand what you are hoping for, walk you through it step by step, and make sure you get there. Michelle answers her own phone and is quickest by text, so ask us anything, at any point, however small it feels.
Michelle Dubner DRE #01496647 Jon Dubner DRE #02118617 Equity Union