Move-up buyers
Selling Your Home and Buying the Next One
Doing both at once is where most people panic. We plan the two sides on one timeline so the dates work for you instead of against you.
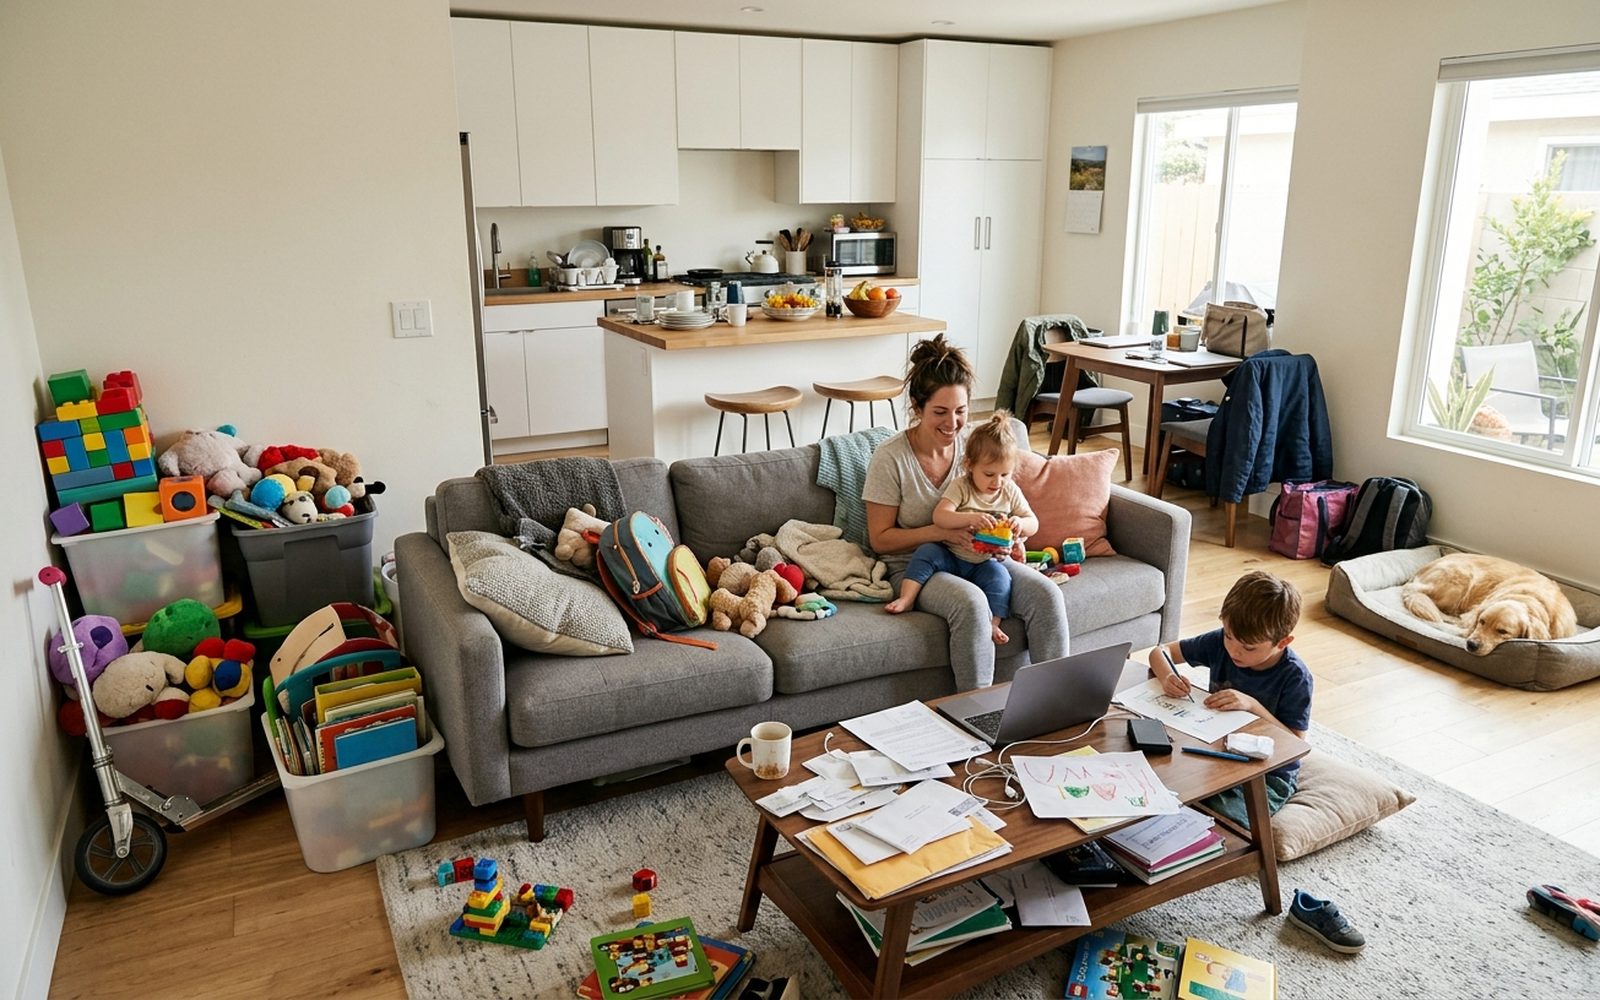
When the House That Fit Five Years Ago Doesn't Anymore
The kids are sharing a room. The home office is a corner of the kitchen table. The yard that seemed fine before the dog arrived now feels like a postage stamp. You've been talking about moving for a year or two, and every time the conversation stalls on the same worry: how do we sell this house and buy the next one without everything falling apart?
Clients say it to us in almost the same words: "I need someone who can handle everything. I can't juggle all of this." Work doesn't pause. Practices, homework, and dinner don't pause. And now there are two sets of deadlines, two sets of paperwork, and a moving truck to schedule in between.
Moving up is one of the most rewarding moves a homeowner can make. It's also the one where a good plan matters most, and that's the part we love building with you.
Let's talk about your next move
What Is Actually Driving the Move
We start here, because it changes the answer more than price does.
Moving up for schools? The assignment sets the map and we work backward from it. For space and a yard? That points one direction. For a view lot? Somewhere else, and usually more per square foot. For newer construction and lower maintenance? A different set of tracts again, usually with Mello-Roos, which is a real monthly number to weigh. Buying multi-generational? Whether a next-gen layout exists narrows things immediately.
Tell us the reason and what your family needs the home to do, and we will tell you which pockets actually deliver that at your number. Explore the neighborhoods, or book a quick call and we will go through it.
Your Current Home Is Where the Plan Begins
Before you tour a single bigger house, we want you to know what your current home can bring and what you'll likely walk away with. That number shapes everything: your down payment, your price range, and which buying strategy makes sense.
We start with a real home value based on recent sales near you. Then we sketch your estimated net: the likely sale price, minus your loan payoff, selling costs, and any credits. Your lender takes it from there to show you what the next home could cost each month.
Sometimes this conversation brings great news. Sometimes it shows that waiting six months, or paying down a debt, would make the move far more comfortable. Either way, you'll decide with real numbers in front of you.
Sell First or Buy First
This is the whole move-up problem, and it can go two ways. The right one depends on your equity, your income, and how much uncertainty you can stand.
Selling first gives you the strongest possible position as a buyer. You know your exact number, you have cash in hand, and your offer has no contingency attached, which in a competitive situation can beat a higher offer. The cost is that you need somewhere to live.
Buying first means one move and no scrambling, but you have to qualify carrying both payments or bridge the gap, and a contingent offer is weaker.
The middle path most of our clients land on is selling first with a rent-back written into the deal. Typically a few days to a couple of months. You get the clean offer and a soft landing, and you pay nothing extra for it.
What tips the decision is usually your real equity and whether a lender will approve you on both payments. Get that answer first, then we map the sequence around it.
Why Sellers Discount Contingent Offers So Heavily
There are three versions and sellers treat them very differently.
- Sale contingency. You have not sold yet and the whole deal waits on it. This is the weakest version, and sellers discount it by more than people expect. Sometimes by more than the gap between two offers.
- Close-of-escrow contingency. Your home is already in escrow and you are waiting on it to close. Much stronger, because most of the risk is behind you.
- Standard buyer contingencies. Inspection, appraisal and loan, which protect your deposit on any purchase.
The practical read: getting your own home into escrow first changes how your offer is received, often more than raising your price would.
Getting at Your Equity Before the Sale Closes
Four routes, and the timing on the first one catches people out constantly.
Home equity line of credit. Often cheapest, but most lenders will not open one on a home that is already listed for sale. If you want that option, open it before you list. People discover this in the wrong order all the time.
Bridge loan. Purpose-built for exactly this. Short term, more expensive, lets you buy before you sell.
Buy-before-you-sell programs. A company effectively guarantees the purchase of your current home so you can make a non-contingent offer. Costs more than a rent-back, solves the same problem.
Selling first with a rent-back. Still the cheapest, because you pay nothing extra for it.
Talk to a lender about all four before you decide, and we will tell you honestly which one your situation actually calls for.
The Tax Piece, and the Prop 13 Piece
Two different things, and move-up buyers need both.
Capital gains. Most people selling a home they lived in owe nothing. You can exclude up to $250,000 of gain filing single, $500,000 married filing jointly, if you owned and lived in it 2 of the last 5 years and have not used the exclusion in the past 2. Gain is sale price minus what you paid plus improvements and costs, not the check you walk away with.
Your property tax basis. Moving up resets your assessed value to the new purchase price. If you have owned a long time under Proposition 13, that increase can be substantial and it is permanent. It belongs in your monthly math from the start.
If you are 55 or older, Proposition 19 may let you carry your base-year value to the new home instead, anywhere in California, up to three times, within two years of selling. If the replacement costs more, the difference is added rather than the basis resetting. Worth asking your CPA before you decide anything.
Two Escrows, One Calendar, Zero Guessing
Here's what our coordination looks like when you move up with us.
- A shared timeline. We map both transactions on one calendar, including every contract deadline on each side.
- Your home, ready to shine. We give you a prep plan and our trusted vendors handle the painting, repairs, cleaning, and staging, so you're not spending weekends running a project.
- The search runs in parallel. While your home is being prepared, we're watching for the next one. Tell us your must-haves through our custom home search request.
- Negotiating with both closings in mind. Closing dates, rent-backs, and contingencies get written to protect the move as a whole, not just one sale.
- Moving day, planned. We help you think through movers, storage, and the order of keys so there's no night without a bed.
You can see how each side works on our selling process and buying process pages.
Living in a House That's for Sale
Keeping a home show-ready with kids, pets, and a full schedule is hard. We'll help you set showing windows that respect your routine, pack away the clutter early so daily resets are quick, and plan where the dog goes when buyers come through. A focused launch with strong pricing also helps keep the stretch of showings as short as possible.
Plan for the first weekend too. That's often when interest is highest. Many sellers plan a day out, a visit with family, or an afternoon at the park so buyers can tour freely and nobody at home has to tiptoe around.
Living in a House That's for Sale
Living in a house that is for sale
Where Move-Up Plans Usually Go Sideways
Buying on an optimistic sale price. If your next purchase assumes your home sells at the top of the range, a lower offer can squeeze everything. We plan around a realistic number.
Forgetting the cost of the move itself. Movers, storage, a short rental, utility deposits, and a few new pieces of furniture add up.
Assuming the tax picture. Gains on a primary residence often get favorable treatment, but the rules depend on how long you've owned and lived there and on your own finances. Talk to a CPA before you sell.
Waiting for the perfect alignment. There is no month where your house sells high and the next one is cheap. Both sides of the trade sit in the same market, so when prices rise your sale gains and your purchase costs more, and when they fall the reverse happens. Your equity travels with the market either way. The question worth answering is not whether the timing is perfect. It is whether the gap between what you net and what you need works for your family right now.
Where Move-Up Plans Usually Go Sideways
A room nobody has touched yet
What a Well-Run Double Move Feels Like
One repeat client told us, "Once we found a house, we had to close within 10 days and they made the process so much easier." That's the feeling we're after. Tight timelines, handled calmly.
Timing is where the plan earns its keep. In August 2026, homes in the Santa Clarita Valley averaged 50 days on market, according to the Southland Regional Association of REALTORS®, so we build both sides of your move around a realistic timeline instead of a hopeful one. Michelle has been licensed since 2004, and most of our business comes from past clients and their referrals. A lot of them are people who bought their first home with us and came back when it was time to move up.
Let's Map Out Your Move
You don't need to know the order yet. Book an appointment or call 661-219-5517 and we'll look at your equity, your goals, and your timeline together. Even if the move is a year away, starting the plan now makes the whole thing calmer. We help move-up buyers throughout all six Santa Clarita Valley communities and across Los Angeles County.
Frequently Asked Questions
Should I sell my home before buying the next one?
What is a contingent offer?
What is a rent-back?
Can I use equity from my current home before it sells?
How do you time two closings so we don't end up without a place to live?
Will I owe taxes on the sale of my current home?
How much will I walk away with after selling?
How do we keep the house ready for showings with kids and pets?
Do you handle both the sale and the purchase?
Keep exploring
Ready to make your move with Dubner Real Estate Group?
Meet the team
You would be working with our team
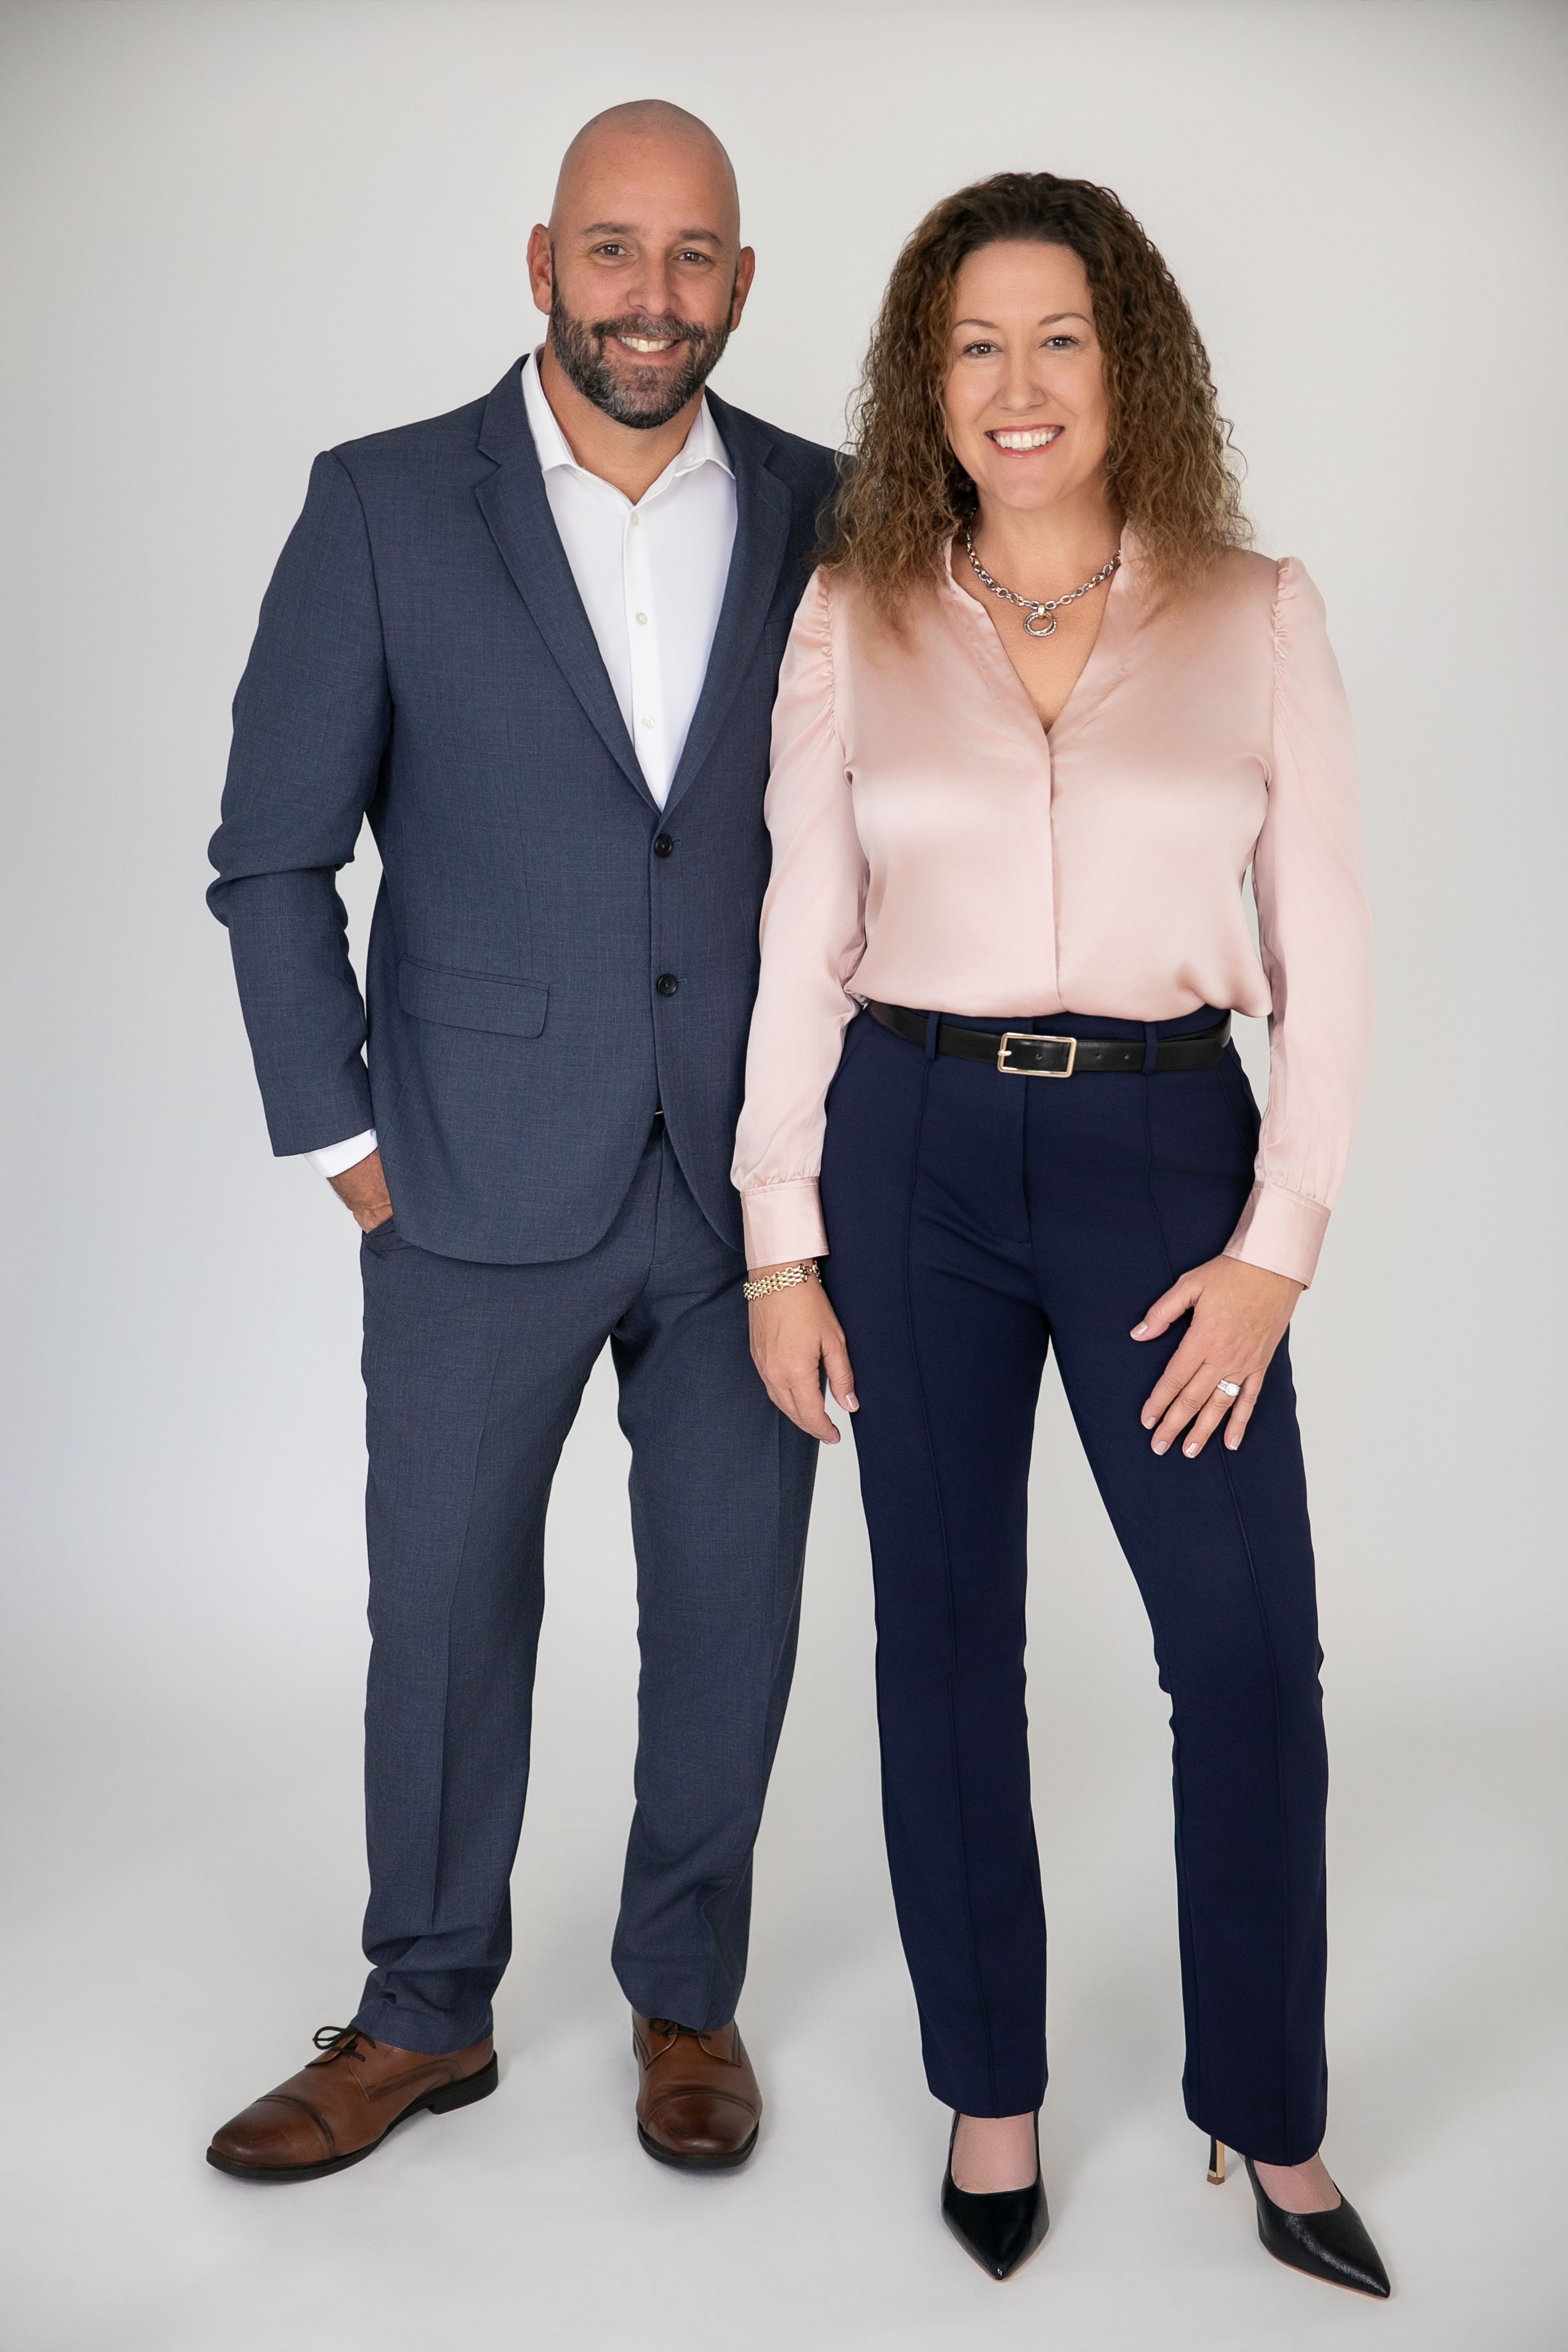
We are Michelle and Jon Dubner, husband and wife, and Dubner Real Estate Group is ours. Our team is here to serve you: to understand what you are hoping for, walk you through it step by step, and make sure you get there. Michelle answers her own phone and is quickest by text, so ask us anything, at any point, however small it feels.
Michelle Dubner DRE #01496647 Jon Dubner DRE #02118617 Equity Union