VA & military buyers
Buying a Home With a VA Loan
You earned this benefit. We make sure it actually works for you here, from the funding fee to the appraisal to an offer a seller will take seriously.
Thank You for Serving. Now Let's Talk About Home.
Whether you're active duty with orders in hand, a veteran ready to settle down, or a surviving spouse, buying a home with military benefits comes with its own set of questions. How does the VA loan work? Will sellers take my offer seriously? Can we find something before the report date?
You've spent years operating on someone else's schedule. Buying a home should feel like the opposite, a decision that belongs to you and your family. We want you to understand your options fully, choose the right home without being rushed by guesswork, and feel protected every step of the way.
A quick note on what this page is and isn't. We're real estate agents, not lenders. We'll explain how the process generally works, and your VA-approved lender will confirm the details for your situation.
Let's talk about your next move
How a VA Home Loan Works, Plainly
A VA loan is made by a private lender and partly guaranteed by the U.S. Department of Veterans Affairs. That guarantee is why lenders can offer terms that are often friendlier than other loans.
Below is every piece of it that will actually change what you sign. Read the funding fee one twice, and then read the paragraph after the list, because the fee is where veterans most often hand over money they never owed in the first place.
- Eligibility. It's based on your service history. Your lender can help you request a Certificate of Eligibility, which confirms you qualify.
- Down payment. Eligible borrowers can often buy with no down payment, though you can still choose to put money down.
- No monthly mortgage insurance. VA loans don't carry the monthly private mortgage insurance that many low-down-payment loans require.
- The funding fee. Most borrowers pay a one-time VA funding fee, which can usually be rolled into the loan instead of paid at closing. As of September 2026 the purchase rates are 2.3 percent of the loan on a first use with nothing down, 1.65 percent with 5 percent down, and 1.4 percent with 10 percent or more down. If you have used the benefit before and put nothing down, it jumps to 3.6 percent, though 5 or 10 percent down brings it back to the same 1.65 and 1.4. On an $800,000 purchase with nothing down, that is a difference of about $18,400 on a first use versus roughly $28,800 on a later one, which is a real reason to ask whether a small down payment pays for itself.
- It's for your home. VA loans are meant for a home you'll live in as your primary residence.
- Property standards. A VA appraiser checks that the home meets minimum requirements for safety and soundness, along with value.
And the fee many people pay when they did not have to. You are exempt from the funding fee entirely if you receive VA compensation for a service-connected disability, if you are entitled to that compensation but receive retirement or active duty pay instead, if you are a surviving spouse of a veteran who died in service or from a service-connected disability, or if you are an active duty Purple Heart recipient. If your disability rating comes through after you close, you can apply for a refund of the fee you already paid. People miss that one constantly.
Rates, limits and fees change. Confirm yours with a lender who writes VA loans regularly, and bring us the Certificate of Eligibility number when you have it so we can write the offer correctly the first time.
California Has Its Own Veteran Program Too
Most of the veterans we sit down with have never heard of this one, which is exactly why it is on the page.
CalVet Home Loans is a separate program run by the State of California for eligible veterans, with its own terms and requirements. It is not a version of the federal VA loan and it is not a replacement for it. It is a second door. Which door is better depends entirely on your situation, and both answers happen. For some buyers CalVet is the better fit. For others the federal VA loan wins.
Here is the part worth carrying with you. If you walk into a lender's office and ask about the VA loan, the VA loan is what you will be quoted, because that is the question you asked. Nobody is keeping anything from you. You just have to ask the wider question.
So ask it this way: which of these two is better for me, and why. Then have a lender who knows both put them next to each other before you choose. It is one extra sentence at the start of a conversation, and it can be worth real money.
You Can Probably Buy More Than You Think
With full entitlement, there is no VA loan limit on a zero-down purchase. The old county caps only bind when your entitlement is partial, meaning you already have a VA loan on another property.
What actually sets your number is what a lender will approve on income, debts and credit. Not a VA ceiling.
That distinction matters here, because plenty of veterans rule out Valencia, Stevenson Ranch or a gated community assuming the benefit will not stretch. Nothing about a premier community disqualifies VA financing.
Get a real pre-approval from a lender who writes VA regularly, not occasionally, and have them pull your Certificate of Eligibility so you know your true entitlement before you shop.
The One Thing That Kills More Military Deals Here Than Anything Else
VA does not approve condos unit by unit. It approves the whole development. The project is either on the VA approved list or it is not.
That single fact ends more military purchases in this valley than credit, income or price ever do, and it is checkable in about ten minutes, before you fall in love with a unit.
If a project is not approved, it can sometimes be submitted for approval, but that takes time most buyers on a report date do not have. Send us any attached home you are considering and we will confirm approval status before you write.
Occupancy, and What Happens When Orders Change
A VA loan requires you to certify that you intend to live in the home as your primary residence, generally moving in within about 60 days of closing. Buying purely to rent out is not permitted at origination.
What is permitted is a 2 to 4 unit property where you live in one unit and rent the others, and you can count some of that rental income toward qualifying.
Then life happens. PCS orders are the most common accepted reason to move out and rent the home, and with documented orders it does not put you crossways with the occupancy rule even if you have not hit a year. What matters is that you genuinely intended to live there when you closed, and did.
Keep your orders. Tell your lender. And if you want to use the benefit again where you are headed, ask about second-tier entitlement before you start looking.
Using the Benefit More Than Once
It is not one and done. Plenty of our clients have used it two or three times.
Sell and pay off the VA loan and your entitlement is generally restored in full.
Keep the first home. Renting it out after orders, say, and the guaranty stays tied up in it. You may still have remaining entitlement to buy another primary residence, which is called second-tier entitlement. In that case county limits do come back into play and you may need some down payment above that line.
This is worth mapping before you list or buy, because the sequence changes what you can afford on the other end.
Using the Benefit More Than Once
Out back, early
What the Appraisal Will Scrutinize
VA has Minimum Property Requirements covering safety, soundness and sanitation. On most tract homes in this valley that clears easily. On land, horse property and older homes, a few items need looking at early rather than three days before closing:
- A private well has to supply safe, potable water year round, with testing to local health department standards. A shared well needs a recorded written agreement covering access and maintenance.
- A septic system has to be functioning, with no surfacing or failure.
- Roof condition, peeling paint on pre-1978 homes, and anything affecting habitability.
None of that rules out Castaic horse property or an older Newhall home. It means ordering the well test and septic inspection up front and building the timeline around them.
What the Appraisal Will Scrutinize
What the appraiser goes looking for
Helping Your VA Offer Stand Out
Some sellers and agents still carry old assumptions that a VA offer is slower or harder to close. A well-prepared VA buyer can compete, and part of our job is making sure your offer is presented that way.
A strong pre-approval from an experienced VA lender. A lender who closes VA loans often knows how to keep the file moving and can speak confidently to the listing agent.
Clear, clean terms. We shape your offer around what matters to that particular seller, whether that's timing, a rent-back, or flexibility on small repairs.
A personal explanation. We call the listing agent, walk them through your financing, and answer questions before they become doubts.
No agent can promise a seller will accept an offer. We can make sure yours is taken seriously.
Buying on a PCS Timeline
When your move date is set by orders, the calendar drives everything. We start with your report date and plan backward: time to get pre-approved, time to search, the escrow period, and a cushion for surprises.
- We tour homes for you by live video if you can't be here yet, and tell you honestly what the camera doesn't show.
- If one spouse will sign while the other is away, ask your lender and escrow company early about their requirements for a power of attorney. Getting that wrong at the last minute can delay closing.
- We help you think through a backup plan for housing in case closing lands after your arrival.
Moving here from out of state? Our relocation page covers learning the area from afar.
If you're searching from base housing or another state, it helps to narrow your search to two or three areas early. A tighter focus means every video tour counts and you can move fast when the right home appears.
Buying Before You Arrive
You can get pre-approved, search, and go under contract before you physically arrive, and a lot of families do. Many lenders will work off your orders.
The occupancy rule expects you in the home within about 60 days of closing, so your report date and closing date need to line up sensibly. A spouse arriving ahead of you can usually satisfy occupancy.
Practically, we do a lot of video walkthroughs and detailed photo tours for buyers still at their current duty station, and we tell you honestly what a camera cannot show you about a house. Road noise. How steep the street is. What the neighbor is doing.
If there is any way to visit once, even for a long weekend, we recommend it and we will plan a tight tour so every hour counts.
Where We Help
We work across the entire Santa Clarita Valley and Los Angeles County. The reason we ask which of three situations you are in before we talk about houses is that they are genuinely different jobs, and answering the wrong set of questions wastes the time you have least of.
Active duty with orders. Your report date sets the calendar and everything gets planned backward from it, including who signs if one spouse is still at the current duty station, and whether your closing and your arrival land sensibly inside the occupancy window.
A veteran settling down. No deadline, which is an advantage most people waste. This is the version where there is time to pull the Certificate of Eligibility, find out your true entitlement, and check a condo project's approval status before anybody falls for a unit.
A surviving spouse. There is a funding fee exemption that may apply to you, and it is one of the most commonly missed items on this whole page. Whether it reaches your situation depends on the circumstances, which is why it is worth asking about directly rather than assuming either way.
Tell us which one you are and we will answer the questions that actually apply to you instead of the general ones. Send us your criteria through our custom home search and we will start watching the market for you.
Let's Build Your Plan
Share your timeline, whether you have orders, and what you're hoping for in a home. Book an appointment or call 661-219-5517. We'll help you line up an experienced VA lender and map out every step between today and move-in day. If you're not ready yet, we're happy to answer questions now and pick back up when your orders or plans are set.
Frequently Asked Questions
Can I really buy a home with no money down using a VA loan?
What is the VA funding fee, and do I have to pay it?
How do I prove I'm eligible for a VA loan?
Will sellers accept a VA offer?
Can I use a VA loan to buy a condo?
What's the difference between a VA loan and a CalVet loan?
Can I buy a home before I arrive on PCS orders?
Can I use my VA loan more than once?
Does a VA appraisal require repairs?
Keep exploring
Ready to make your move with Dubner Real Estate Group?
Meet the team
You would be working with our team
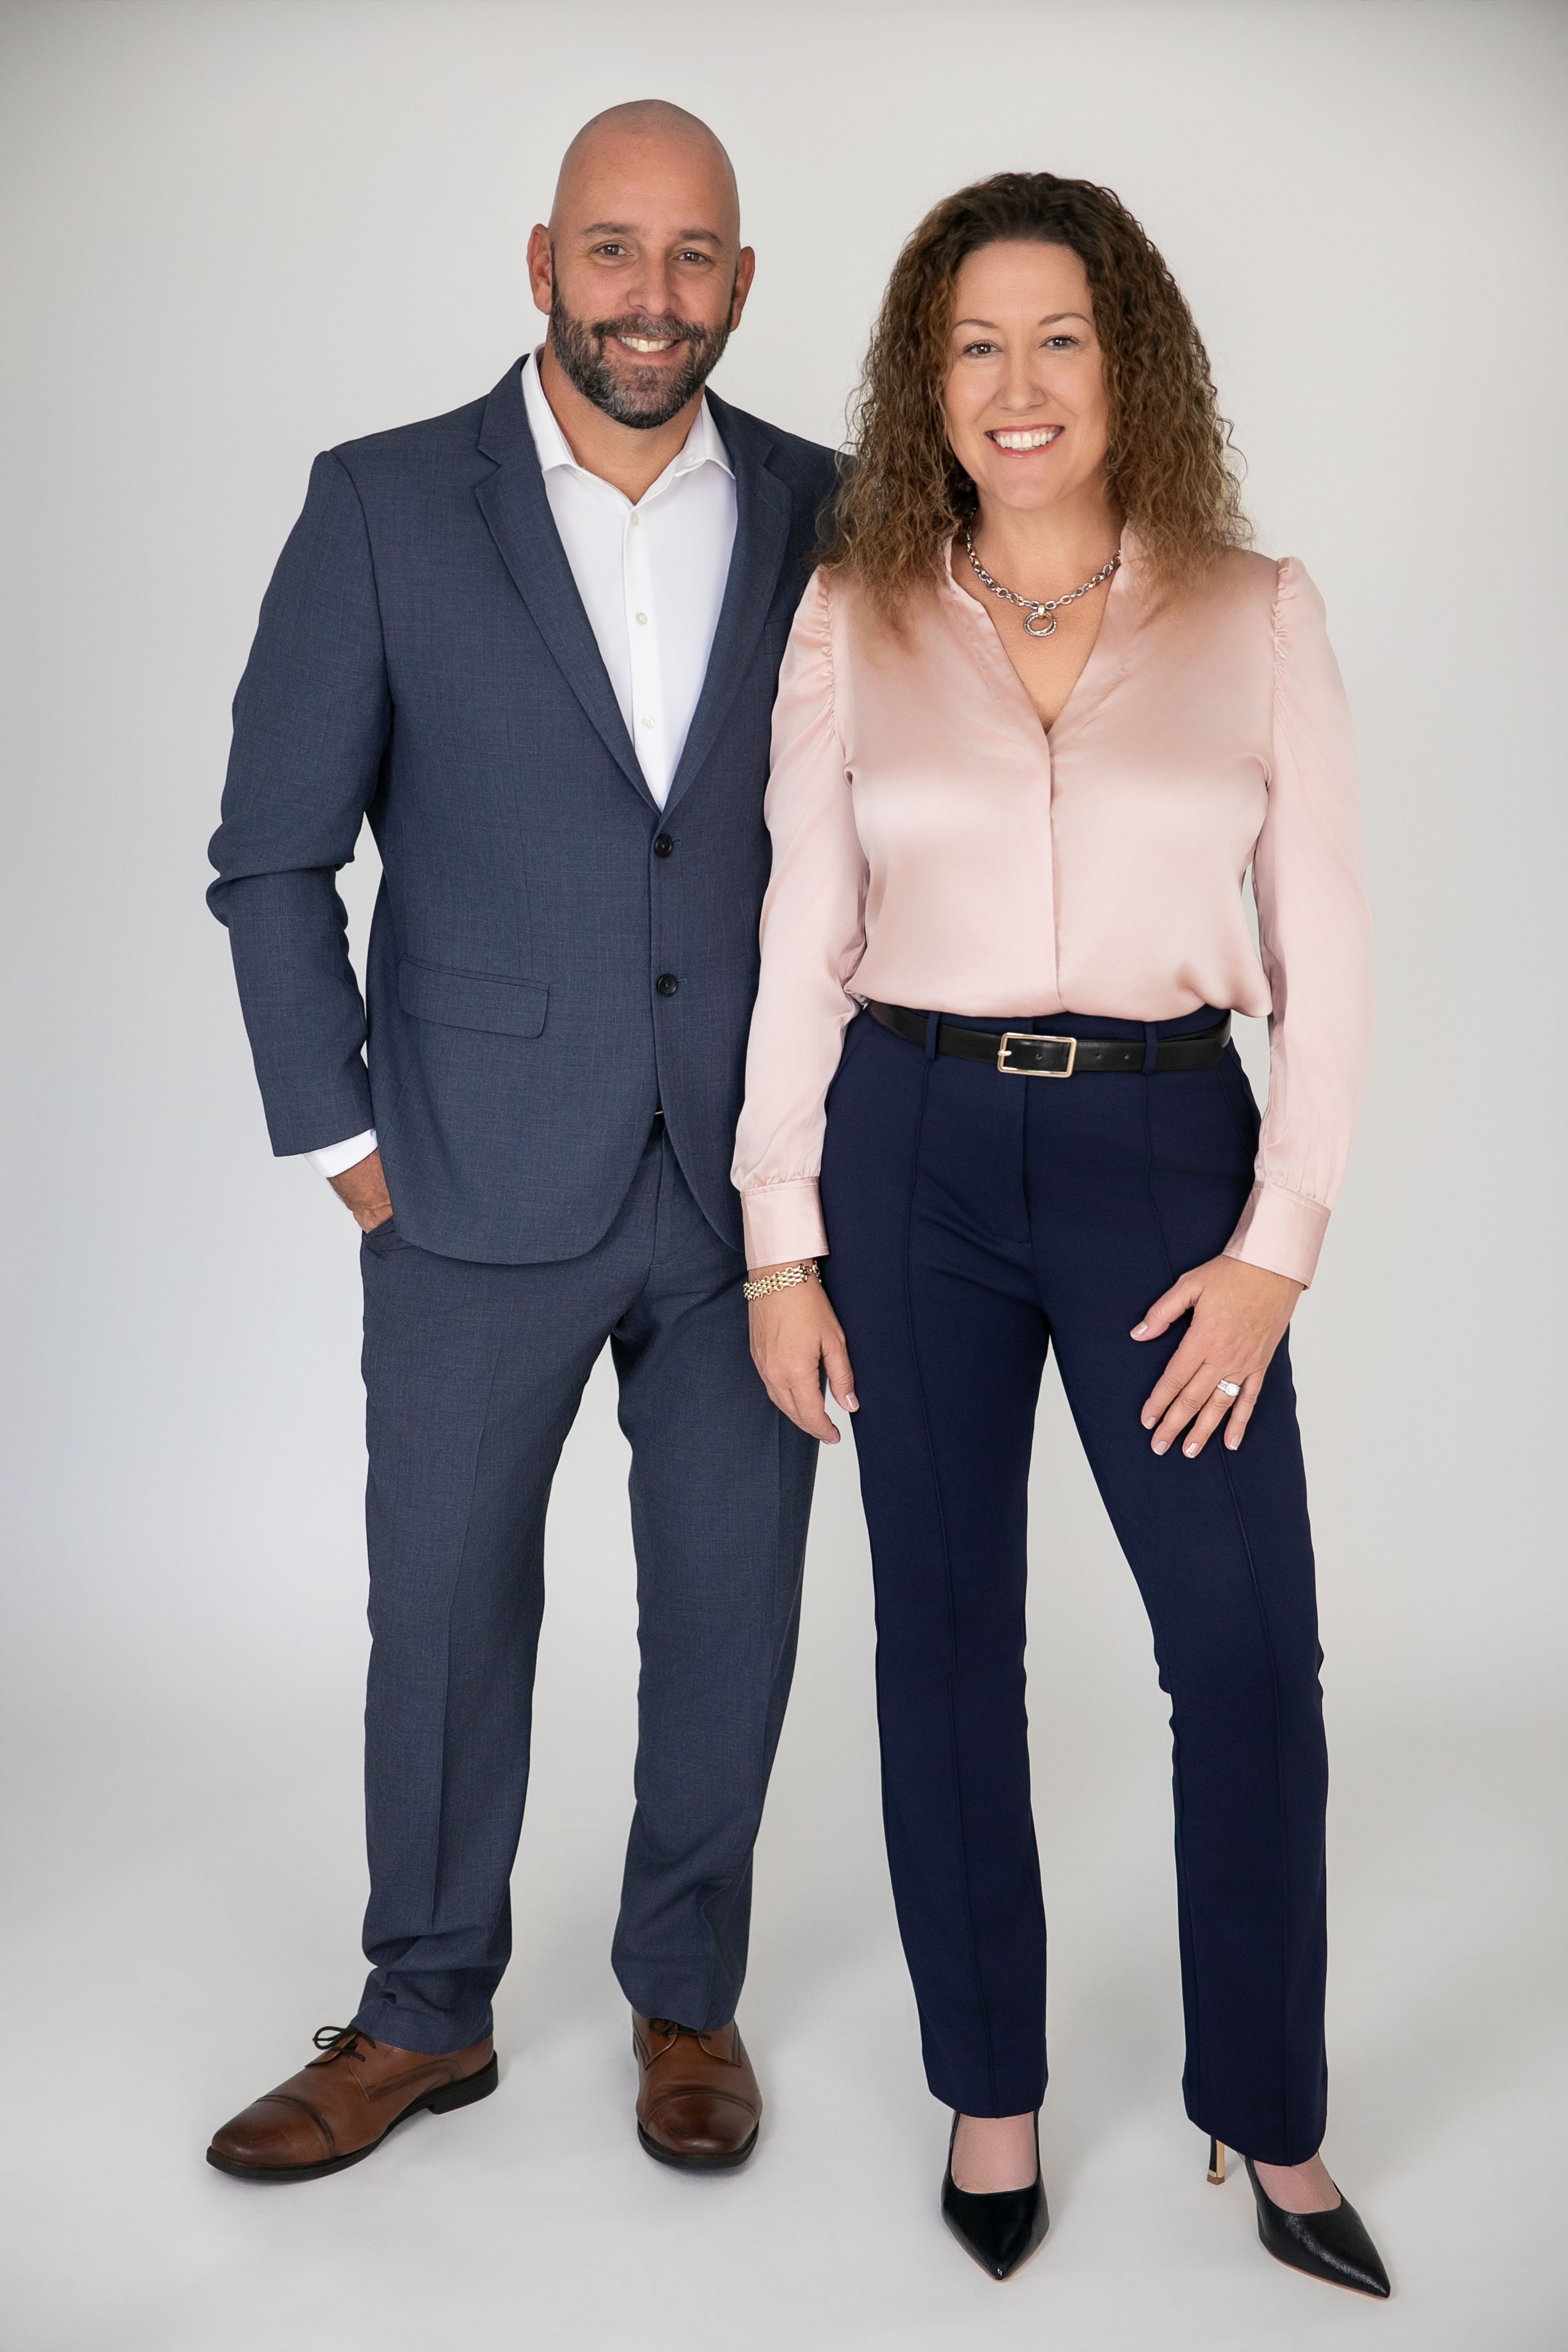
We are Michelle and Jon Dubner, husband and wife, and Dubner Real Estate Group is ours. Our team is here to serve you: to understand what you are hoping for, walk you through it step by step, and make sure you get there. Michelle answers her own phone and is quickest by text, so ask us anything, at any point, however small it feels.
Michelle Dubner DRE #01496647 Jon Dubner DRE #02118617 Equity Union